How Much House Can You Afford? A Simple Affordability Guide
Estimate the home price you can afford from your income, debts and down payment using the 28/36 rule, with a worked example and tips to raise it.
Buying a home is exciting, and it is also the easiest place to overspend. Before you visit a single flat, it helps to know the price range that your income can safely carry. The free Home Affordability Calculator estimates it from your yearly income, your monthly debts, your down payment, the interest rate and the loan term.
Quick answer
A widely used guide is the 28/36 rule: your housing payment should not be more than 28 percent of your gross monthly income, and your total debt payments, including the home loan, should not be more than 36 percent. For a household earning 12,00,000 taka a year with 10,000 a month in other debts, a 9 percent loan over 20 years and 15,00,000 saved for the down payment, the calculator suggests a maximum monthly payment of 26,000, a loan of about 28.9 lakh and a home price of about 43.9 lakh.
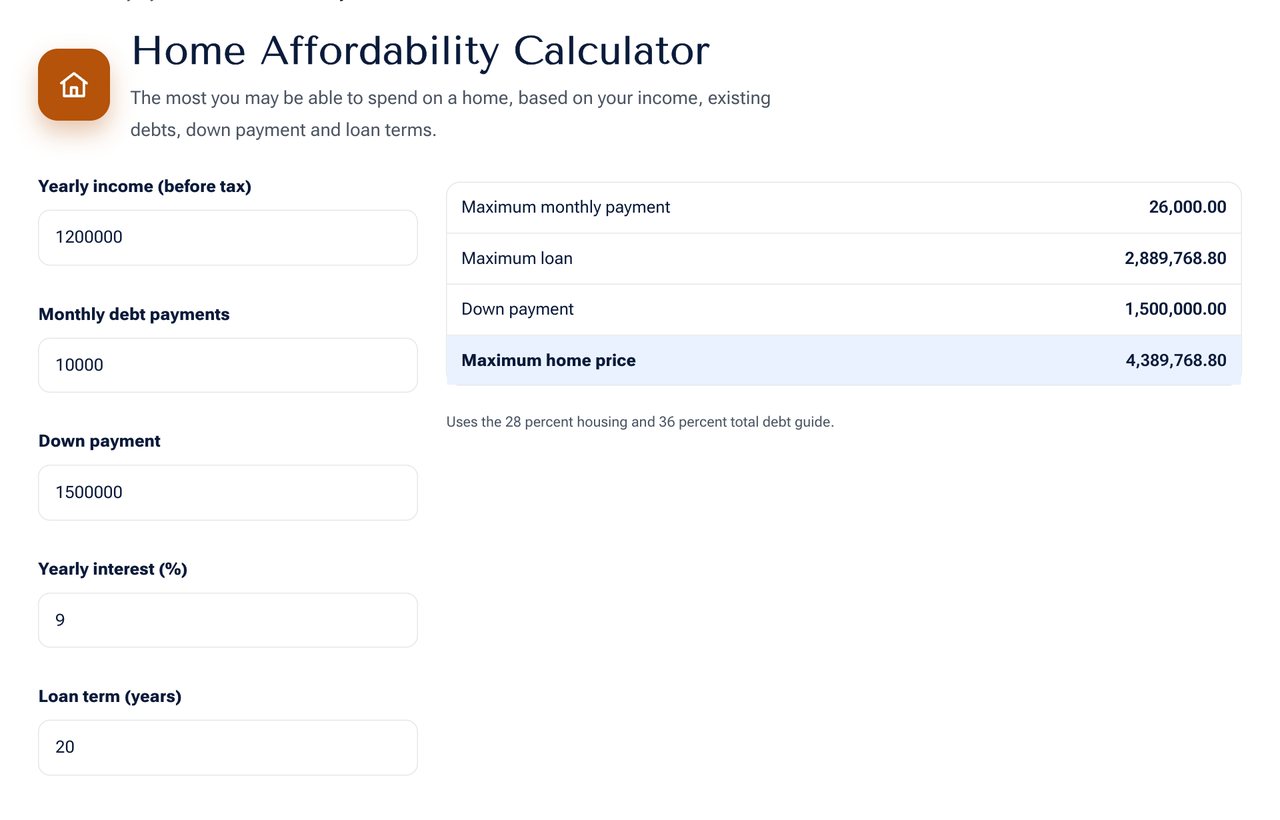 The Home Affordability Calculator with the example household filled in.
How the calculation works
- Divide your yearly income by 12 to get the monthly income: 1,00,000.
- The first limit is 28 percent of that: 28,000.
- The second limit is 36 percent minus your other debts: 36,000 minus 10,000 is 26,000.
- The affordable payment is the smaller of the two: 26,000.
- That payment, at 9 percent for 240 months, supports a loan of about 28.9 lakh.
- Add your down payment of 15 lakh to get the maximum price: about 43.9 lakh.
The tighter limit wins. Notice that your existing debts, not only your income, decide the answer. Clearing a car loan can raise the price you can afford by several lakh.
Why the rule is conservative
The rule was designed so that a family can pay the loan and still cover food, school fees, repairs and savings. A lender may approve more than this, but approval is not the same as comfort. Many households that stretch to the lender's maximum find that every other goal is delayed for years.
How to afford a higher price
- Raise the down payment. Every extra taka you put down is a taka you do not borrow and pay interest on.
- Pay down other debts first. A smaller debt payment frees room under the 36 percent limit.
- Lengthen the term carefully. A 25-year loan allows a higher price but costs much more interest. Compare the total, not just the monthly figure.
- Improve the rate. A lower rate on the same payment lifts the loan size. Shop between banks and ask about reducing balance schemes.
- Use a co-borrower. A second income raises the limit, but both people become responsible for the loan.
Costs beyond the price
Budget for registration, stamp duty, legal and valuation fees, agent or developer charges, moving, furnishing, utility connections and a repair reserve. In many markets these add 5 to 10 percent of the price on top of the figure above.
Steps to use the calculator
- Enter your gross yearly household income.
- Enter the total of your monthly debt payments, such as car, personal and card loans.
- Enter the down payment you actually have.
- Enter the rate and the term in years.
- Read the maximum monthly payment, the loan and the price. Then try a lower rate or a larger down payment.
Sources and further reading
- The 28/36 guideline is widely used by lenders and housing counsellors; the consumer-finance basics are explained in How Loan EMI Is Calculated.
- For an exact schedule on a specific offer, use the Loan Amortization Schedule.
Frequently asked questions
Is the result a promise from a bank? No. It is a planning estimate. Banks apply their own credit rules.
Should I use gross or net income? The rule uses gross income. If your take-home pay is much lower, be extra cautious.
Does the rule suit Bangladesh? It is a sensible starting point anywhere. Local costs, such as rent you would no longer pay, can adjust it.
What if I want to rent instead? Compare the monthly cost of owning, including maintenance and the interest you give up on your down payment, with the rent you would pay.
Next step
Open the Home Affordability Calculator and enter your own figures. Then check the payment on a specific home with the Mortgage Calculator.