How to Calculate a Car Loan EMI: Price, Down Payment and Interest
Work out the monthly payment, total interest and real cost of a car loan from the price, down payment, trade-in, rate and term, with a worked example.
A car is often the second biggest purchase a family makes after a home, and the loan is where most of the extra cost hides. The sticker price is only the beginning: the interest you pay over the years can add hundreds of thousands of taka. The free Car Loan Calculator shows the monthly payment and the full cost before you sign anything.
Quick answer
Enter the car price, your down payment, any trade-in value, the yearly interest rate and the number of years. The calculator returns the loan amount, the monthly payment, the total interest and the total cost of owning the car on paper. For a car priced at 25,00,000 taka with 5,00,000 down, at 9.5 percent over 5 years, the loan is 20,00,000, the monthly payment is about 42,000 and the total interest is about 5,20,000.
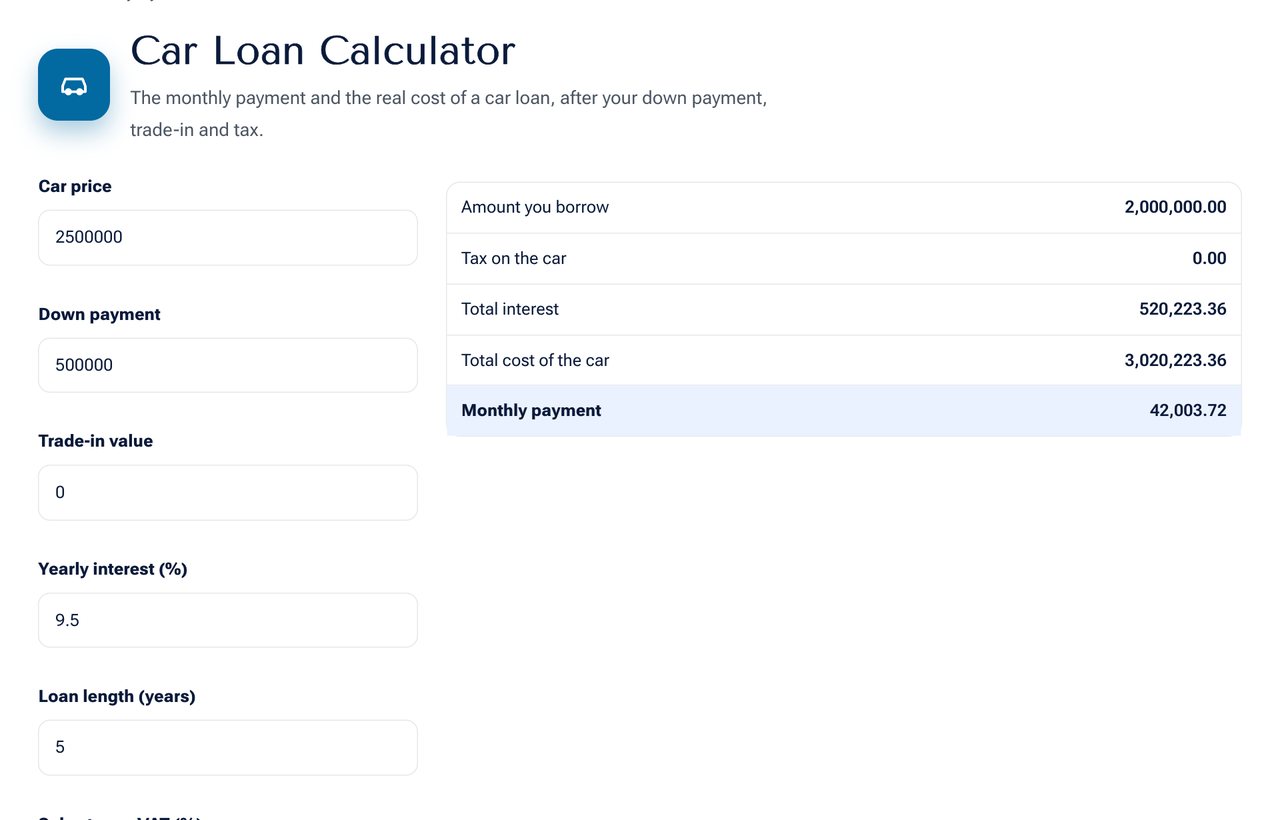 The Car Loan Calculator with the example values already filled in.
How the number is worked out
The loan amount is the price, plus any sales tax or registration you finance, minus the down payment and the trade-in. The monthly payment then comes from the standard instalment formula, the same one banks use for any fixed-rate loan:
payment = loan x r / (1 - (1 + r) to the power of minus n), where r is the monthly rate (yearly rate divided by 12) and n is the number of months.
In the example above, r is 0.095 / 12 = 0.0079 and n is 60. The first month's interest is about 15,833 and the rest of the payment reduces the loan.
What you really pay
| Item | Amount (taka) |
|---|---|
| Car price | 25,00,000 |
| Down payment | 5,00,000 |
| Loan amount | 20,00,000 |
| Monthly payment (60 months) | about 42,000 |
| Total interest | about 5,20,000 |
| Total paid including down payment | about 30,20,000 |
So the car that is listed at 25 lakh costs about 30 lakh by the end. That 5 lakh gap is the price of borrowing. Add insurance, registration, fuel and servicing, and the true cost of ownership is higher still.
How each choice changes the payment
- A bigger down payment lowers the loan and the interest in direct proportion. Each extra lakh you put down saves roughly 26,000 taka of interest in this example.
- A shorter term raises the monthly payment but cuts the interest sharply. Over 3 years the same loan costs about 3 lakh in interest instead of 5.2 lakh.
- A lower rate matters more than most people expect. Compare at least three lenders, and ask whether the rate is flat or reducing balance, because a flat rate of 9 percent is much more expensive than a reducing rate of 9 percent.
- A trade-in works like a down payment. Get its value in writing before you calculate.
Steps to use the calculator
- Enter the on-road price, not only the showroom price.
- Enter the down payment you can pay without touching your emergency fund.
- Add a trade-in value if you have one.
- Enter the rate quoted by the bank and the term in years.
- Read the monthly payment and test a shorter and a longer term.
Mistakes to avoid
- Choosing a loan by the monthly payment alone. A long term makes a car look cheap each month while costing far more in total.
- Ignoring fees such as processing charges, valuation and insurance that the lender asks you to finance.
- Forgetting that a car loses value. After five years the car is worth much less than the 30 lakh you paid.
- Stretching the budget. A common guide is to keep the car payment, insurance and fuel together below about 15 percent of your monthly income.
Is the calculator the same as the bank's offer?
It should be close. Banks may round the payment, charge fees or use day-count rules, so the final figure on your offer letter can differ by a small amount. Use the calculator to compare offers and spot a bad one, and use the bank's own schedule for the final numbers.
Sources and further reading
- Bangladesh Bank publishes policy rates and guidance for lenders: bb.org.bd.
- For the full month-by-month split of a loan, see How to Read a Loan Amortization Schedule.
Frequently asked questions
Is a bigger down payment always better? It reduces interest, but keep enough savings for emergencies. Do not empty your reserve to save a little interest.
Can I pay the loan off early? Many banks allow it but charge a fee. Ask before you sign, and check whether extra payments reduce the term or only the instalment.
What is the difference between flat and reducing rate? A flat rate charges interest on the original amount for the whole term. A reducing rate charges it on the falling balance, so it costs less at the same quoted percentage.
Does the calculator include insurance? No. Add insurance and registration to the price if you finance them.
Next step
Try your own numbers in the Car Loan Calculator. For a general loan, use the Loan Calculator or the Loan Amortization Schedule.