How Inflation Reduces the Value of Your Money
Understand how rising prices shrink the buying power of savings, with a worked 10-year example and simple ways to protect your money.
Money kept idle loses value because prices rise. The free Inflation Calculator shows what a sum will be worth, or what you will need, after some years.
Quick answer
At 6 percent inflation, something that costs 1,00,000 today will cost about 1,79,000 in 10 years. Equally, 1,00,000 kept in cash will buy only what 55,800 buys today.
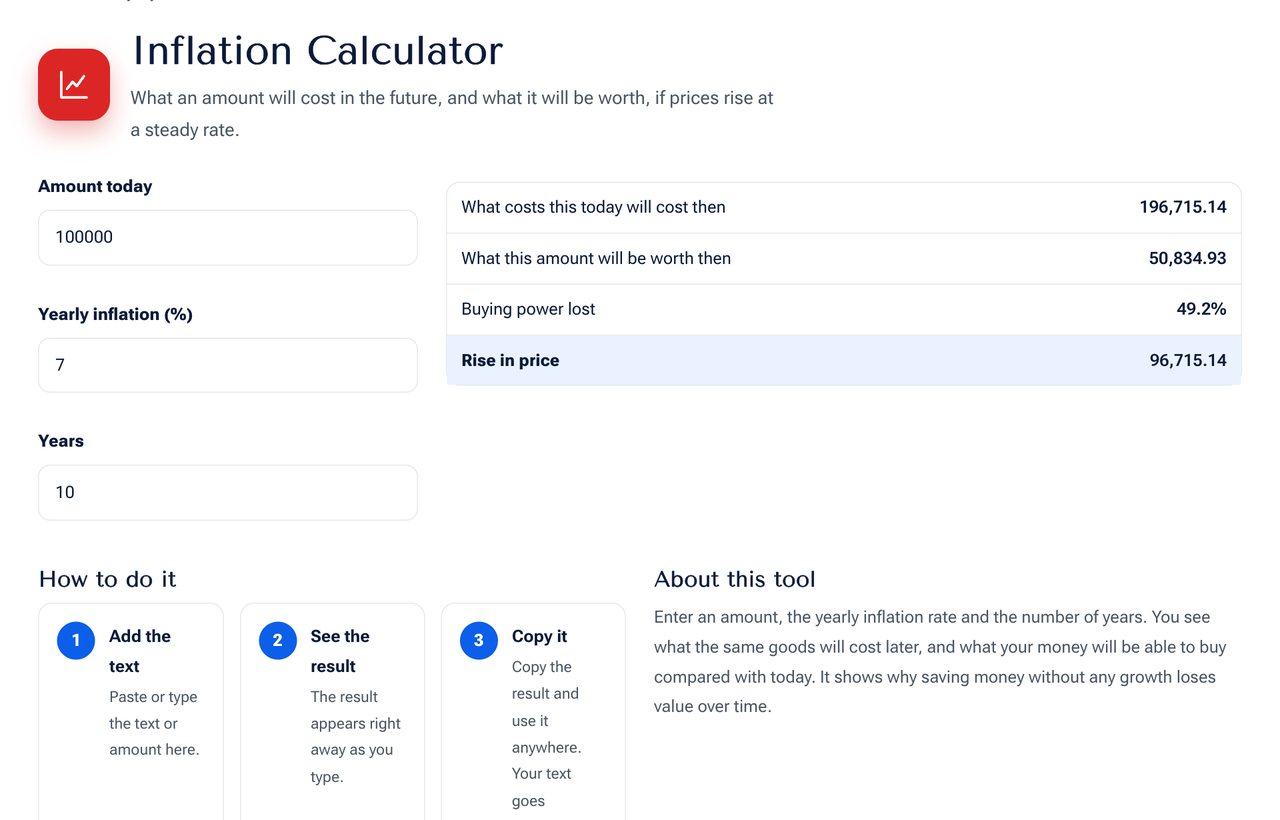 The Inflation Calculator tool on shobfree.com, ready to use in your browser.
The idea in one example
Suppose rice, rent and school fees all rise by 6 percent a year. After one year your 1,00,000 buys what 94,000 bought. After ten years it buys little more than half. Nothing was lost from your account, but its power was.
How to use the calculator
- Enter the amount.
- Enter the yearly inflation rate you expect.
- Enter the number of years.
- Read the future cost and the value in today's money.
Why this matters for your plans
- Savings goals: a goal of 5,00,000 in 10 years should be raised for inflation.
- Retirement: monthly expenses will be much higher then.
- Fixed incomes: a pension that does not rise loses value each year.
Ways to protect your money
- Earn a return at least equal to inflation on long-term savings.
- Invest in assets that tend to rise over time, within your risk level.
- Increase your savings every time your income rises.
- Avoid keeping large sums in cash for years.
A longer example for retirement
If you spend 30,000 taka a month today and inflation averages 6 percent, you will need about 53,700 a month in 10 years, 96,000 in 20 years and 1,72,000 in 30 years, only to buy the same things. This is why a retirement plan built on today's expenses falls short. Always plan with the future cost, not the present one.
Real return
Your real return is roughly your return minus inflation. A deposit paying 7 percent when inflation is 6 percent is growing your buying power by only about 1 percent a year. If the deposit pays less than inflation, your money is shrinking in real terms even though the balance goes up.
Prices in Bangladesh over time
Everyday prices show the effect clearly. Items that cost 50 taka a decade ago often cost 80 to 100 today, which is an annual rise of about 5 to 7 percent. The exact figure depends on the item and the year, so check the latest consumer price index published by the Bangladesh Bureau of Statistics when you plan.
Simple rules to stay ahead
- Ask for raises that match at least the inflation rate.
- When you sign a long contract, such as rent, include a yearly step based on a fixed percentage.
- Review your savings plan every year and increase it with the cost of living.
Sources and further reading
- Bangladesh Bureau of Statistics publishes the national consumer price index: bbs.gov.bd.
Frequently asked questions
Which inflation rate should I use? Check the recent official figure and use a slightly cautious number for long plans.
Is inflation always bad? Mild inflation is normal. It hurts when your income and savings do not keep up.
Is the inflation of food and the general rate the same? No. Different items rise at different speeds. Use a rate that matches your own spending.
Next step
Open the Inflation Calculator with your own numbers. To plan the monthly amount, use the Savings Goal Calculator.